From AAA to Equity: CLO MVOC and Equity NAV (13 Jul 2026)
Below are tables presenting the MVOC (AAA–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 13 July 2026.
Independent, clear, and trusted — CLO Research Group provides actionable insights for CLO debt and equity investors.
Below are tables presenting the MVOC (AAA–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 13 July 2026.
A sample of 569 EU CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 60% are excluded.
A sample of 1,646 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
This week saw 22 line items of longer-dated EU CLO single-B bonds, totalling EUR 66.8 million, trade with released cover levels according to SCI's BWIC data. All of the bonds have reinvestment periods ending in 2029 or 2030. DMs ranged from a tight 870 to 973.
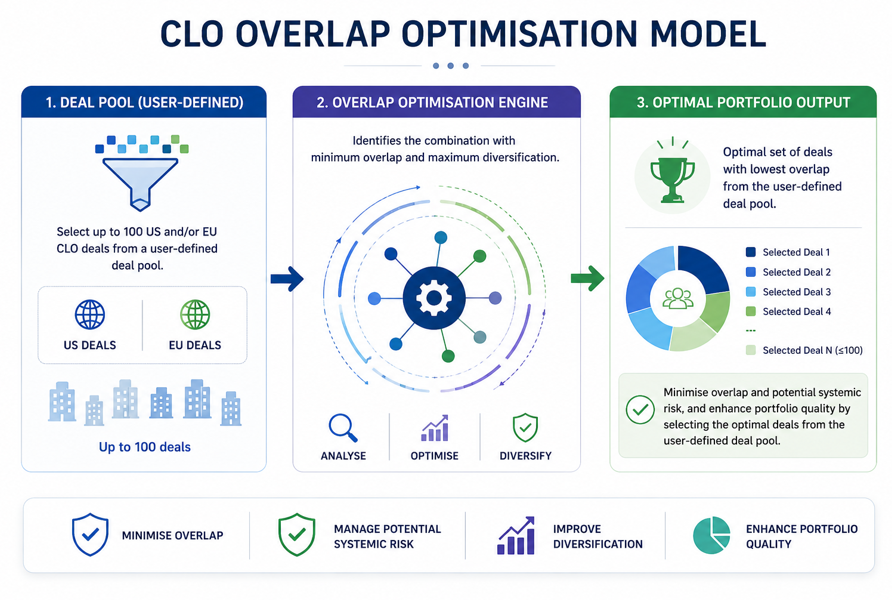
Please find the download link in this article for the overlap optimisation model. The model allows users to select up to 100 US and/or EU CLO deals from a user-defined pool of deals and identifies the optimal combination to minimise overlap.
The 2018 vintage has experienced the highest impairment rate so far, with approximately 19% of single-B rated tranches having become impaired. Unfortunately, this rate is expected to rise further...
A sample of 573 EU CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 60% are excluded.
A sample of 1,647 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
A sample of 351 fully repaid single-B tranches is included in this study. Overall, their performance has been very impressive, with an average realised IRR exceeding that of equity tranches. In addition, single-B tranches generally carry lower risk than equity, given their second-loss position in the capital structure.
A sample of 1,651 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
A sample of 572 EU CLO deals (vintage 2013–1H 2025) is included in this study. A sample of 572 EU CLO deals (vintage 2013–1H 2025) is included in this study. Static deals and those with a collateral pool factor below 60% are excluded from the analysis.
Below are tables presenting the MVOC (BB–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 26 June 2026.
This model tracks reported WAS and WARF trends across 129 US BSL CLO managers, with monthly data dating back to April 2013. Select up to five manager-vintage combinations from the dropdown menus, and the chart will instantly compare their WAS and/or WARF levels.
Over the past year, more than 2,000 BWIC line items for rated EU CLO bonds have been observed. Among them, 261 line items across the AAA to single-B rating spectrum were called at par. Of these, 218 had a cover price at or above par, while 43 had a cover price below par.
The table below shows the average annualised prepayment rates for each seasoned manager in the first, second, third, fourth and fifth years of the post-reinvestment period (post-RP). The sample includes seasoned deals that had exited their reinvestment periods by 31 December 2024. Eight EU CLO managers have maintained single-digit annualised prepayment rates during either the first and second years or the second and third years of the post-RP period across their seasoned deals.