From AAA to Equity: CLO MVOC and Equity NAV (17 Jul 2026)
Below are tables presenting the MVOC (AAA–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 17 July 2026.
Independent, clear, and trusted — CLO Research Group provides actionable insights for CLO debt and equity investors.
Below are tables presenting the MVOC (AAA–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 17 July 2026.
A sample of 538 fully repaid EU CLO BB tranches with disclosed issue prices or DMs is included in this study. Overall, their performance has been very impressive, with an average realised IRR of 10.1%.
Below are tables presenting the MVOC (AAA–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 13 July 2026.
A sample of 560 EU CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 60% are excluded.
A sample of 1,646 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
This week saw 22 line items of longer-dated EU CLO single-B bonds, totalling EUR 66.8 million, trade with released cover levels according to SCI's BWIC data. All of the bonds have reinvestment periods ending in 2029 or 2030. DMs ranged from a tight 870 to 973.
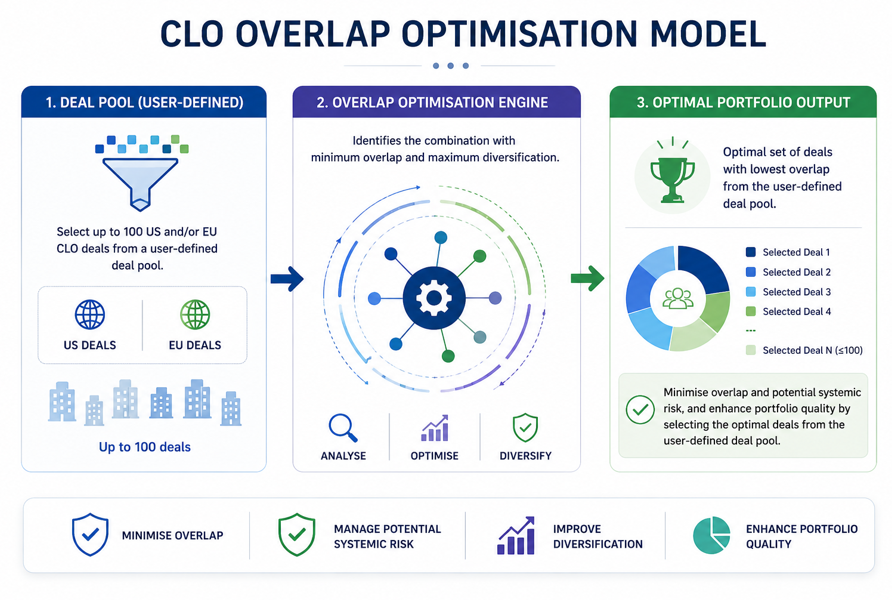
Please find the download link in this article for the overlap optimisation model. The model allows users to select up to 100 US and/or EU CLO deals from a user-defined pool of deals and identifies the optimal combination to minimise overlap.
The 2018 vintage has experienced the highest impairment rate so far, with approximately 19% of single-B rated tranches having become impaired. Unfortunately, this rate is expected to rise further...
A sample of 573 EU CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 60% are excluded.
A sample of 1,647 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
A sample of 351 fully repaid single-B tranches is included in this study. Overall, their performance has been very impressive, with an average realised IRR exceeding that of equity tranches. In addition, single-B tranches generally carry lower risk than equity, given their second-loss position in the capital structure.
A sample of 1,651 US BSL CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 55% are excluded.
A sample of 574 EU CLO deals (vintage 2013–1H 2025) is included in this study. Deals with a collateral pool factor below 60% are excluded.
Below are tables presenting the MVOC (BB–B) and equity NAV of US BSL and EU CLO deals by vintage, based on asset prices as of 26 June 2026.
This model tracks reported WAS and WARF trends across 129 US BSL CLO managers, with monthly data dating back to April 2013. Select up to five manager-vintage combinations from the dropdown menus, and the chart will instantly compare their WAS and/or WARF levels.