2021-Vintage European CLOs: Telecoms and Chemicals Lead Sub-80 Loan Exposure (Updated)
The five largest industries by sub-80 exposure account for about half of the total exposure to assets priced below 80.
The five largest industries by sub-80 exposure account for about half of the total exposure to assets priced below 80.
US BSL CLO pricing gaps are generally wider than they have been over the past year, particularly for BB tranches. The AAA–BB gap currently stands at 421bps, placing it at the 95th percentile over the past 26 weeks and the 87th percentile over both one and two years. The BBB–BB gap of 268bps is also relatively wide, ranking at the 90th percentile across all three periods.
The table below groups the deals into quartiles by BB MVOC, showing that weaker market-value coverage is associated with greater exposure below each price threshold. The relationship between MVOC and annualised sales volumes is less pronounced.
The table below groups the deals into quartiles by BB MVOC, revealing a clear association between weaker market-value coverage and higher exposure below each price threshold.
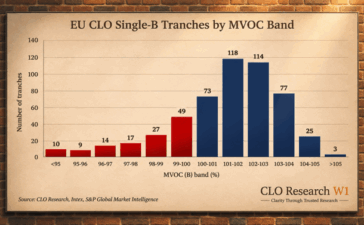
The broader EU CLO single-B market continues to exhibit significant mark-to-market (MTM) pressure, with a substantial proportion of tranches showing limited or negative MV collateral coverage cushions.
Please find the download link below for the overlap optimisation model. The model allows users to select up to 100 US and/or EU CLO deals from a user-defined pool of deals and identifies the optimal combination to minimise overlap.
The study covers a sample of 556 EU CLO deals issued between 2013 and the first half of 2025. Static deals and those with a collateral pool factor below 60% are excluded from the analysis. The sample of 556 CLO deals also shows an average 8.8% of collateral priced below 80, concentrated in the 60–70 and 70–80 bands, which together account for 7.3%. Exposure below 60 is comparatively limited at approximately 1.5%.
US CLO new-issue volume reached $126.8bn across 271 deals in the first nine months of 2026, down 17.6% by volume and 15.0% by deal count compared with the same period in 2025. EU CLO issuance held up considerably better over the same period. New-issue volume remained broadly stable at €48.3bn across 114 deals, with volume down just 0.5% and deal count up 1.8% compared with the first nine months of 2025.
If you are an investor and would be interested in trial access, the Basic content is available on a two-week trial once the trial subscription agreement is in place.
The table below presents the IRRs by vintage for fully liquidated EU CLO deals from the 2013 to 2023 vintages, based on a sample of 134 deals.
The table below presents the IRRs by vintage for fully liquidated US CLO deals from the 2012 to 2023 vintages, based on a sample of 958 deals.
2025 is on course to be another record-breaking year. This article explores some of the key ingredients behind strong primary issuance.
Among the top performers are Oak Hill Advisors, UBS AM, and Palmer Square Capital Management.
In year-to-date 2025 and throughout 2024, managers have, on average, broadly tracked the loan index across all three inception-to-date annualised metrics: total return, market value (MV) return, and interest return. The benchmark loan index used is the Morningstar LSTA U.S. B/BB Ratings Loan Index. Nonetheless, several managers—such as OHA, Golub Capital, and UBS AM—have continued to distinguish themselves with above-average inception-to-date alpha since 2020, while others have consistently lagged behind the index.
Late last week, approximately $240 million of long-dated AAA tranches (with reinvestment periods ending between 2029-2030) changed hands, as shown in the table below. Top-tier prints were mainly in the 150 DM area. For example, MAGNE 2024-42A A1 traded with a cover bid of 150 DM.
A more objective way to evaluate a manager’s capability is by examining the inception-to-date gross annualised collateral return of their deals, measured relative to the relevant loan indices and assessed on an unlevered basis. This provides a clearer measure of true alpha generation.
How Have EU CLO Managers Stacked Up Against the Loan Index Since Inception? This study examines the long-term performance of 218 EU CLO deals from the 2015–2019 vintages, using the Morningstar European Euro-Denominated Loan Index as the benchmark. As of 19 March 2025, EU CLO managers, on average, had outperformed the loan index on an inception-to-date basis—driven primarily by principal value return outperformance—while their interest return remained broadly in line with that of the index.
According to independent analysis by CLO Research, Generate Advisors has consistently delivered outperformance against the Morningstar LSTA U.S. B/BB Ratings Loan Index on an unlevered basis in recent years. Here’s a set of interview questions from CLO Research, accompanied by responses from Rizwan Akhter, Head of Generate Advisors.
Our website attracts a steady stream of visitors each month, ensuring your job postings receive significant visibility among a relevant audience. Increase your chances of finding the ideal candidate by listing your opportunities on CLOPremium—completely free of charge.
According to CLO Research’s independent analysis, RRAM has delivered consistently robust results from both equity and debt perspectives. Here’s a set of interview questions from CLO Research, accompanied by responses from Bhavin Patel, Chief Investment Officer of Redding Ridge Europe.
The table presented in this premium article showcases the trends by displaying the average annual prepayment rates for the first, second, and third years for each manager. These rates are calculated from seasoned deals whose reinvestment periods concluded before April 2024.
CLO equity investors generally prefer slower prepayment rates in the early years after the reinvestment period, as this helps sustain favourable leverage within the structure and supports more efficient funding costs. Moreover, it provides equity investors with additional time to assess the optimal call timing, which has proven particularly valuable in today’s robust market environment. For instance, a deal that exited its reinvestment period in 2022 and experienced a very rapid post-reinvestment period annual prepayment rate, leading to significant deleveraging, would have been under greater pressure to be called at a time when market conditions were less favourable than they are today.
Can AUM Growth and Performance Go Hand in Hand?
According to CLO Research’s independent analysis, Golub Capital has delivered consistently strong results from an investment alpha perspective. Specifically, Golub Capital has achieved substantial outperformance relative to the Morningstar LSTA U.S. B/BB Ratings Loan Index on an unlevered basis over the past several years. Below is a list of interview questions from CLO Research, along with responses from Scott M. Morrison, Managing Director and Head of Broadly Syndicated Loans.
Have you ever wondered how CLO tranche ratings—AAA, AA, A, BBB, and BB—are derived from a portfolio of non-investment grade loans?
Drawing from a sample of 87 EU CLO deals that have either been redeemed or are expected to reach full redemption shortly, equity tranches from the 2020, 2022, and 2023 vintages have delivered notable final IRRs, underpinned by robust equity NAV metrics. As illustrated in the table, their average equity NAVs surpassed 100%, underscoring strong performance.
Although every CLO deal is unique, analysing historical prepayment rates during the post-RP period is valuable. It reveals manager tendencies, distinguishing those who consistently deliver lower prepayment rates from those with higher rates.
The table below lists the top MVOC quartile managers and their annualised sale volumes.
A sample of 1,511 US BSL CLO deals (vintage 2013–2023) is included in this study. Deals with a collateral pool...
Please refer to the table below for the ten largest CLO managers and their global CLO collateral AUM, broken down by US BSL, US MM, and EU CLO AUM as of September 30, 2024.
This study examines a sample of 218 deals from the 2015 to 2019 vintages, utilising the Morningstar European Euro-Denominated Loan...
A sample of 1,546 US BSL CLO deals (vintage 2013–2023) is included in this study. Deals with a collateral pool...
A sample of 496 EU CLO deals (vintage 2013–2023) is included in this study. Deals with a collateral pool factor below 60% are excluded. Market Value Over-Collateralization (MVOC), for instance, at the BB tranche level, is calculated by dividing the collateral market value (MV) by the sum of CLO liabilities (AAA to BB). MVOC is a crucial point-in-time metric for pricing CLO-rated tranches, closely monitored by primary and secondary market participants. If you’re curious to explore our premium insights or would like a personal walkthrough of the website via Zoom, feel free to reach out at info@clopremium.co.uk.
While each CLO deal is different, understanding the historical prepayment rates based on the original collateral balance during the post-RI period for each manager remains highly beneficial. Analyzing these rates offers insights into the tendencies of different managers, highlighting those who consistently achieve lower prepayment rates and those who tend to experience higher rates in the post-reinvestment phase. To illustrate these trends, the following table presents the average first-year, second-year, and third-year annualized prepayment rates for each manager, based on data from their seasoned deals that have passed their reinvestment end dates. These historical post-RI prepayment rates could be useful as cash flow modeling inputs for each manager.
Based on 558 post-2012 US CLO deals that have been redeemed or paid off so far, those from the 2014 and 2018 vintages performed the worst. However, the sample size for the 2018 vintage deals is still relatively small. Deals from the 2020 and 2022 vintages performed the best, with median deals registering IRRs of...
The following EU CLO deals issued and priced their single-B tranches this year. These were initially structured for delayed issuance...
YTD, 70 BSL CLO deals have been reported to have undergone resets. Among these, 15 deals from the 2022–2023 vintages have reduced their cost of funding by an average of 61 bps, while also extending their reinvestment periods by about 2.7 years on average.
The table below shows the top-performing managers with the most 2013–2019 deals that are in the 90th percentile category. Notably, CSAM stood out as the most successful and consistent manager in delivering good returns to equity investors. Other successful managers include Oak Hill Advisors, KKR Financial Advisors, Goldentree Asset Management, Neuberger Berman, Generate Advisors, Fortress Investment Group, and Anchorage Capital Group.
At first glance, one might assume that managers with higher portfolio spreads tend to perform well during favorable market conditions but struggle during downturns. However, upon closer analysis of the average alpha performance within each category, this assumption is only partially valid and not universally applicable.
A sample of 313 seasoned deals (2016–2019 vintage deals) managed by 57 US CLO managers is included in this study. The benchmark loan index used is the Morningstar LSTA US B-BB Ratings Loan Index.
This study includes a sample of 93 more recent deals (closed in 2021 and Jan 2022) managed by 46 managers, using the Morningstar European B Ratings Loan Index as the benchmark loan index. The table below illustrates the relative standing of each EU CLO manager based on their latest average total alpha metrics (as of 26th June 2023) . A score of 98%, for instance, indicates that the manager’s total return alpha is at the 98th percentile, meaning their total return alpha metric exceeds that of 98% of their peers.
Overweight indicates that the manager’s average industry exposure exceeds the sample average exposure by 1 percentage point. Conversely, underweight means the manager’s average industry exposure is less than the industry average exposure by 1 percentage point.
Discover the main disparities between the seasoned US BSL and EU CLO equity tranches in relation to annual distributions and final equity net asset value (NAV) realisation values necessary to achieve a 12.0% internal rate of return (IRR) target. Explore the reasons why median EU CLO equity tranches have shown higher annual distributions compared to their US equivalents.
Securitisation can certainly play a crucial role in facilitating the mobilisation of institutional capital into infrastructure financing, especially for sustainable infrastructure and clean energy projects. Additionally, it can help banks recycle their balance sheets into originating new loans to finance such infrastructure initiatives.
In the CLO market, the terms "CLO performance" or "resilience" can have varying definitions. It is essential to note that...
This study expands its analysis to include a sample of 90 more recent deals (closed in 2021) managed by 46...
The final IRR of a 2.0 CLO equity tranche very much depends on the final equity NAV realisation. There are 20 US CLO managers with at least one deal registering an IRR of over 15%.
A sample of 197 deals (2015–2019 vintage deals) managed by 38 managers is included in this study. The benchmark loan index used is the Morningstar European Euro Denominated Loan Index.
The top five US CLO managers for each WARF category are typically larger managers with a CLO AUM of $8 billion or more.
At CLO Research, we provide genuinely independent first-hand CLO research content that is highly relevant to the investing community. We can save you precious time and resources in assessing CLO managers through manager scoring based on relative return performance rather than deal metrics.
A sample of 198 deals (2015–2019 vintage deals) managed by 39 managers is included in this study. The benchmark loan...
This article details the track record of redeemed static deals.
Which redeemed deals delivered an equity IRR of over 12.0%? 2020 vintage deals delivered extraordinary IRRs. 2012 vintage deals did well...
This article endeavours to highlight some of the key drivers of 1.0 US CLO equity tranches' outperformance.
This research report is now available to bloomberg terminal users.
This webinar was jointly hosted by Sheil Aggarwal, Head of SCI Valuations, and Poh-Heng Tan, Founder of CLO Research in...
Yesterday’s US CLO BB BWIC totalled USD 40.39m in original face amount across 12 lines. MAGNE and SAND were covered closest to par at 99.57 and 99.51, respectively. CIFC had the tightest dealer DM at 510 bp.
The six EU single-A CLO tranches in yesterday’s BWIC totalled €19.5 million in current face amount, with all six levels reported as covers. Four were covered below par, and cover prices ranged from 99.18 to 100.16. Dealer DMs spanned 68 bp, from 201 bp to 269 bp.
CLO Research Group is planning a specialist workshop for CLO market professionals, focusing on practical approaches to CLO investment analysis, relative value and secondary-market trading.
The A–BBB gap stands out. At 105bp, it is wider than roughly 88% of observations over both the past year and the past two years. It is the only gap in the table above its full-period median.
US CLO exposure to the Scientific Games 6/24 covenant-lite TLB totals $1.48 billion across 880 CLOs managed by 56 managers, with an average exposure of 0.43% per deal.
EU CLO pricing gaps show a clear divergence across the capital structure. Based on gaps between the tightest weekly DMs by rating, AA and A remain tightly priced relative to AAA against the full-period history. BBB and BB offer wider differentials than were typical over the past year, although both remain below their longer-term medians. Single-B stands out, with its gap to AAA close to the widest levels observed over the past two years.
US CLO exposure to the MHS Holdings covenant-lite term loan totals $239.5 million across 105 CLOs managed by four managers.
The chart below shows the resulting trend in new-issue US CLO BB DMs.
Across the 2021-vintage European CLOs in the sample, an average of 15.64% of the original collateral balance fell into price bands below 80. Against this backdrop, single-B tranches from this vintage face significant idiosyncratic credit risks. Around 37% of the single-B tranches in the sample had MVOC below 100%, contributing to market concerns about potential impairment across parts of this segment of the EU CLO market. At the lower end, Bridgepoint CLOs 2 and 3 had just 6.47% and 6.17% below 80, respectively. The five RRE deals had sub-80 shares ranging from 7.34% to 8.50%, with each holding less than 0.2% below 60. Capital Four CLO III also had relatively limited exposure, with 7.68% below 80 and 1.61% below 60.
US CLO exposure to Hertz Corp totalled $600.0m across 320 CLOs managed by 31 US CLO managers, with an average exposure of 0.60% per deal.